8 Best Value Added Services for Worldpay Merchants to Drive Loyalty and Data
Compare 8 Worldpay value added services, from Zeal loyalty on Worldpay payment terminals to gift cards, DCC, cash advance and PCI DSS support.
The best Worldpay value added services are the ones that bring customers back and turn card payments into usable data, without changing how you take payments. This guide covers eight that a UK Worldpay merchant can use: card-linked loyalty from Zeal on supported Worldpay payment terminals, plus seven services from Worldpay itself, namely gift cards, Dashboard and Insights reporting, dynamic currency conversion, pay by link and Virtual Terminal, dispute and fraud tools, a business cash advance and SaferPayments PCI DSS support.
Key takeaways
- Zeal adds loyalty on top of the Worldpay estate. On supported Worldpay payment terminals, Zeal recognises customers when they tap, enrols them in a couple of taps and rewards them during the payment, while Worldpay continues to process every payment.
- The other seven services come from Worldpay. Each is listed on Worldpay's UK website, so you can ask about it through your existing Worldpay relationship.
- Check the terminal and the terms first. Supported models vary, and every service has its own eligibility, pricing and contract terms.
- Agree how customer data will be used. A card reference can still be personal data, so settle consent and data requirements before you switch anything on.
How we put this guide together
Zeal is a Worldpay partner and one of the eight services below, so we have a commercial interest in this topic. We list Zeal first because it is the service we know first-hand; the order is not a ranking. The other seven are Worldpay value added services from Worldpay's own range, described from its UK website and checked on 10 October 2026. We have not measured how Worldpay's services perform, so we describe what Worldpay says each one does and what to check before you use it.
Worldpay value added services at a glance
Service | Provided by | Where it runs | Best fit |
|---|---|---|---|
1. Card-linked loyalty | Zeal, on supported Worldpay terminals | On the payment terminal, next to the payment app | Merchants with returning customers |
2. Gift cards and stored value | Worldpay | In store, with virtual cards online | Seasonal gifting peaks |
3. Dashboard and Insights reporting | Worldpay | Online portal | Every merchant; multi-provider businesses |
4. Dynamic currency conversion | Worldpay | On the payment terminal | International visitors |
5. Pay by link and Virtual Terminal | Worldpay | Browser, links and invoices | Phone orders and deposits |
6. Dispute management and FraudSight | Worldpay | Back office and portal | Chargebacks and card-not-present fraud |
7. Business cash advance | Worldpay, provided with Liberis | Repaid from card sales | Seasonal cash flow and stock |
8. SaferPayments PCI DSS support | Worldpay | Portal, phone, email and chat | Every card-accepting merchant |
Table 1. The eight services at a glance, from Zeal's and Worldpay's own websites, checked 10 October 2026.
1. Card-linked loyalty on Worldpay payment terminals (Zeal)
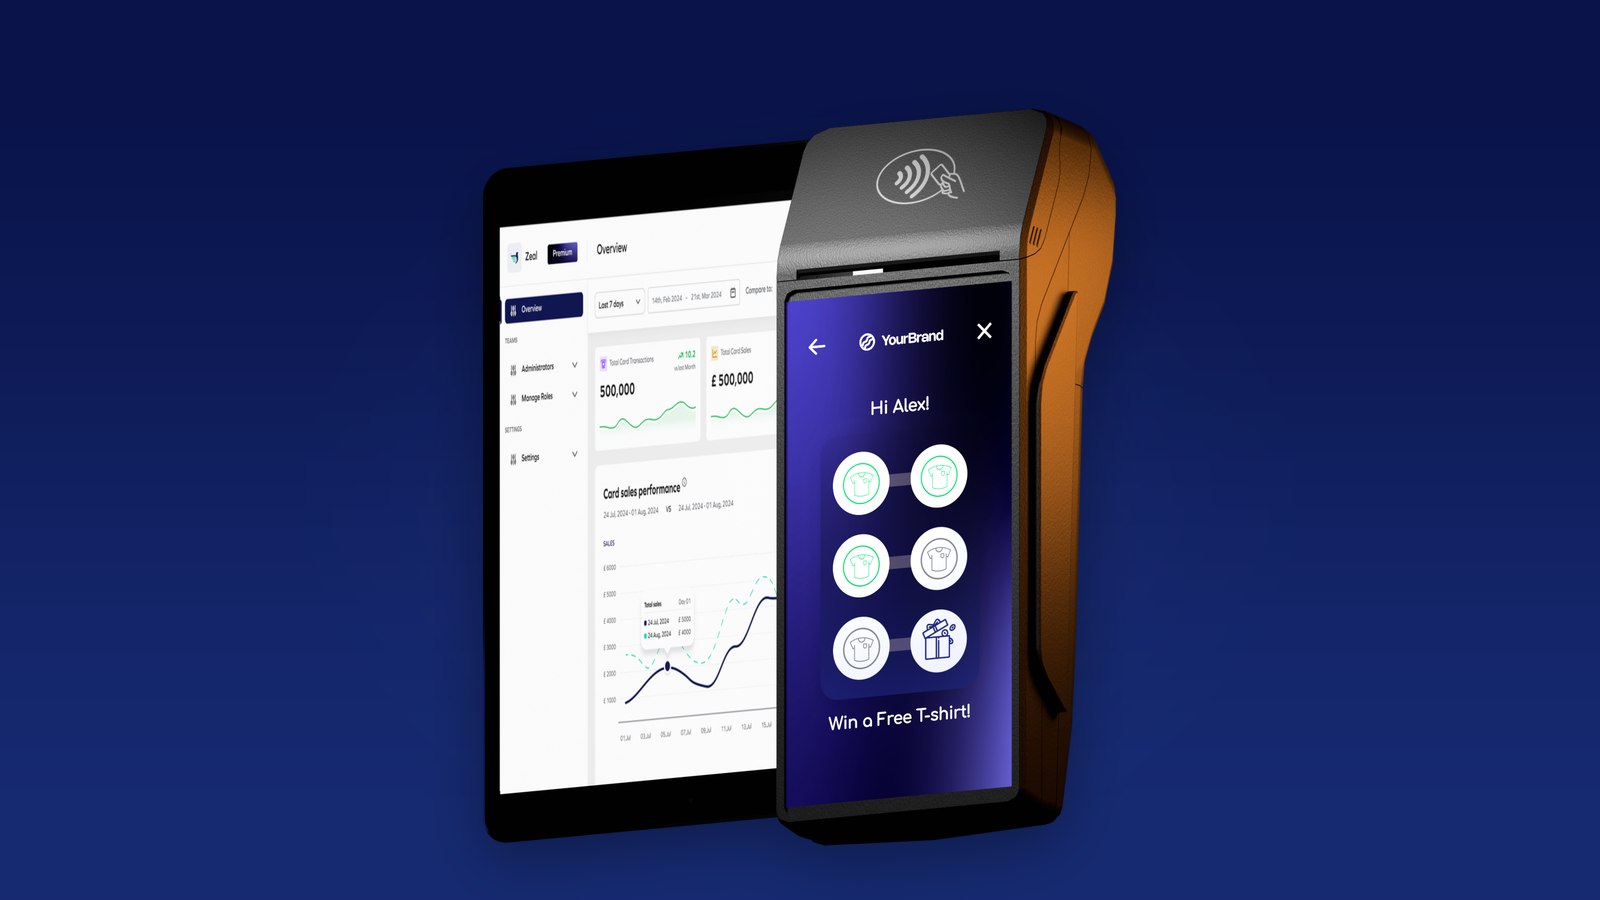
Zeal works with Worldpay. On supported Worldpay payment terminals, Zeal recognises customers when they tap, enrols them in the merchant's loyalty programme and rewards them during the payment, with no app, no QR code and no plastic card. A customer joins in a couple of taps on the screen and is recognised automatically on later visits, earning points, stamps or vouchers as they pay. The merchant sees each regular's visit frequency, spend, favourite time of day and time since the last visit.

Zeal is software that runs next to the payment app. It does not process payments and does not change how a merchant takes payments or when they are paid. Branded receipts, which can show the customer's loyalty balance and a next-visit offer, are live with Worldpay, and Zeal's range also includes Zeal Pledge, which lets customers pledge 30p towards the merchant's rising costs and processing fees. Cards made up 64% of all UK payments in 2025, according to UK Finance, so most payments already involve the card that recognition relies on.
Best fit: cafés, restaurants, bakeries and shops where the same customers return every week.
What to check: supported models vary, so we confirm your exact terminal before anything is switched on; Worldpay's UK site currently lists the DX8000 mobile and DX4000 countertop terminals. Loyalty is part of Zeal's Premium plan, provided through your payment provider on a revenue share or an annual licence.
2. Gift cards and stored value
Worldpay's UK small-business page lists gift card processing, describing "gift, reward and stored value solutions" that help merchants attract new customers and encourage repeat business. Its gift card page says features may include customised or pre-designed cards, variable or preset values, virtual gift cards, management of lost and stolen cards, and simple analytics and online reporting, and Worldpay names Valutec gift and loyalty cards among its programmes. Gift cards are prepaid value, so they sit comfortably alongside rewards earned through Zeal.
Best fit: retailers and hospitality venues with seasonal gifting peaks.
What to check: which programme is offered to UK merchants, card production costs, how balances and lost cards are handled, and whether redemptions appear in your existing reporting.
3. Worldpay Dashboard and Insights reporting
The Worldpay Dashboard is Worldpay's online, self-service portal. It shows each stage of a payment in real time, from card sales to settlements and invoices, gives sales totals and breakdowns of card transactions, offers insights into customers' spending patterns and supports reconciliation. For larger businesses, Worldpay Insights consolidates data from all of a business's processors, acquirers and gateways into one cross-provider view, with real-time dashboards for transaction volumes, authorisation rates and customer behaviour trends. Worldpay's tools show what was sold, settled and approved; Zeal adds who came back, how often and when.
Best fit: every Worldpay merchant (Dashboard), and multi-site or multi-provider businesses (Insights).
What to check: who needs access, which reports you export for accounting, and whether Insights is offered for your business size.
4. Dynamic currency conversion and multicurrency pricing
Dynamic currency conversion (DCC) lets an overseas cardholder pay in their home currency. Worldpay's multicurrency page separates its two currency services: DCC "offers currency conversion at the payment stage", while multicurrency pricing "displays converted prices before checkout" and suits e-commerce. Worldpay's in-store page says merchants can accept payments in 30+ currencies.
Best fit: hotels, attractions, airport and city-centre retailers, and any merchant serving international visitors.
What to check: how the rate and conversion charge are shown to the cardholder before they choose, which cards and terminals support DCC, how the merchant's share is calculated, and how staff explain the choice.
5. Pay by link and Virtual Terminal: omnichannel payment processing for retail
Not every sale happens at the counter. Worldpay's small-business range includes pay-by-link, which sends customers a secure payment link with no website or terminal needed, and invoicing. Its Virtual Terminal takes mail-order and telephone-order (MOTO) payments in a browser through the Worldpay Dashboard. Worldpay says it is included as part of Worldpay eCommerce at no additional cost, with no upfront setup fee, no monthly charge and free next-business-day settlement, while standard Worldpay eCommerce charges apply.
Best fit: retailers taking phone orders, deposits and click-and-collect payments, and hospitality businesses taking bookings.
What to check: the eCommerce charges, the fraud tools you need for card-not-present payments, and how phone payments change your PCI DSS self-assessment.
6. Dispute management and FraudSight fraud prevention
Worldpay's dispute management range has four parts. Disputes Deflector uses dispute information from card brands to deflect disputes before a chargeback claim is initiated. Disputes Defender responds to chargebacks for the merchant, using AI to generate arguments for each case. The Disputes Portal lets merchants manage disputes, upload documentation and track outcomes, and the Disputes Direct API offers the same control through an API. FraudSight, which Worldpay says is powered by Ravelin, is an "end-to-end fraud solution set that detects high-risk behaviour before, during and after the transaction occurs".
Best fit: merchants with card-not-present sales, high-value goods or a history of chargebacks.
What to check: which tools are available for your account, who prepares the evidence, and how fees are charged.
7. Business cash advance from Worldpay Business Finance
Worldpay's business cash advance is provided with Liberis. Eligible merchants can receive between £1,000 and £300,000, repaid as a fixed percentage of their credit and debit card sales, so repayments fall when trade is quiet. Worldpay describes one fixed funding fee with no APR, says an advance is typically settled in four to 12 months, and states that it "is an unsecured way of accessing finance and is not a loan". To apply, a merchant needs at least 10 card transactions totalling more than £1,000 a month.
Best fit: seasonal businesses, and merchants funding stock, equipment or a refit.
What to check: the total fixed cost against other finance, personal guarantees (Liberis asks limited companies and LLPs for them), the 14-day right to change your mind, and the fact that taking an advance may affect your credit score even though a quote does not.
8. SaferPayments PCI DSS compliance support
PCI DSS applies to every entity that stores, processes or transmits cardholder data, including merchants, and PCI DSS v4.0.1 has been the sole active version since v4.0 was retired on 31 December 2024. Worldpay's SaferPayments programme offers a web portal, pre-population of up to 90% of the self-assessment questionnaire (SAQ) for certain Worldpay products, scheduling of quarterly external vulnerability scans where applicable, and telephone, email and chat support six days a week. Confirming compliance avoids Worldpay's monthly non-compliance fee, and SaferPayments Managed adds phone-guided reporting.
Best fit: every card-accepting merchant, especially small businesses without an in-house security team.
What to check: which SAQ applies to your set-up. Approved payment terminals help but do not by themselves guarantee compliance, as the PCI SSC's FAQ 1301 explains.
How Zeal works alongside Worldpay integrated payment solutions
Worldpay's current terminals use Android 10 software and PCI-PTS v6-certified hardware, and Worldpay says they work best as standalone payment terminals, pointing merchants who want EPOS and payments combined to its Worldpay 360 bundles. Zeal changes none of that: it works alongside the existing EPOS and payment processing.

On a supported terminal, two pieces of software share the device. The approved payment application keeps control of card reading, authorisation and payment security. Zeal's value-added services layer receives an approved, non-payment reference for an eligible card, checks it against the merchant's loyalty profiles and returns a prompt or a reward. In Zeal's reference architecture, the recognition flow excludes the PIN, CVV, full card number, payment cryptograms and payment keys.
Two cautions apply. Tokenisation does not automatically take an implementation out of PCI DSS scope: the PCI SSC's tokenisation guidelines treat every component of a tokenisation system as part of the cardholder data environment. And a card reference can still be personal data: the ICO's pseudonymisation guidance, currently under review after the Data (Use and Access) Act, says pseudonymised data is personal data in the hands of someone who holds the additional information. Our card-linked loyalty overview explains how recognition, enrolment and rewards fit together.
How to choose the best value added services for merchants on Worldpay
- Pick one goal per service. Repeat visits, international sales, cash flow and fewer disputes need different tools.
- Confirm your terminal and contract. Since January 2023 the PSR's card-acquiring remedies have required the 14 directed firms to cap payment terminal lease and rental contracts at 18 months, followed by a rolling monthly contract.
- Ask how each service is priced. Get the fee basis (per transaction, monthly, licence, revenue share or fixed fee) and any minimum term in writing.
- Agree data and consent up front. The ICO's legitimate interests guidance says legitimate interests can apply to direct marketing only where PECR does not require consent.
- Pilot on one site, then expand. Check the customer journey and the reporting before you roll a service out.
What we have learned adding loyalty to payment terminals since 2019
I co-founded Zeal with Bellal Mohamed in 2019, and I have spent seven years building software that runs on payment terminals. We built the core technology in 2020 and 2021, when Visa recognised Zeal as an up-and-coming solution, and we tested it in the real world for two years, 2022 and 2023, with Ingenico as a strategic partner; merchant feedback guided the improvements that shaped the product. Since 2024 we have added partnerships with Castles and other industry partners.
In my experience, three habits decide whether a value-added service works on a Worldpay estate:
- We confirm the terminal first. In my experience, supported models vary, so we check the exact payment terminal before anything is switched on.
- We deploy through the payment provider. Zeal reaches terminals through our partners' terminal management systems, so merchants install nothing themselves.
- We agree data requirements up front. Integration and customer-data requirements are settled before deployment, alongside the existing EPOS and payment processing.
Step | What happens | Who does it |
|---|---|---|
1. Register | The merchant registers on getzeal.io | Merchant |
2. Confirm | Zeal confirms the terminal and payment setup are supported | Zeal and the payment provider |
3. Agree | Integration and customer-data requirements are agreed | Zeal, payment provider and merchant |
4. Deploy | Zeal is deployed through the provider's terminal management system | Payment provider |
5. Go live | Customers join in a couple of taps and are recognised on later visits | Merchant and customers |
Table 2. How a merchant switches Zeal on, taken from Zeal's own product documentation.
The outcome so far: more than 30,000 merchants activated on Zeal across payment providers, seven live UK payment partners (Adyen, DNA Payments, Elavon, Lloyds Cardnet, NMI, Viva Wallet and Worldpay) and 4 million payment terminals in our partners' signed activation pipeline. We have raised $14 million in total, and the team won Team of the Year at the UK FinTech Awards 2026.
Frequently asked questions
What Worldpay value added services can UK merchants use?
Worldpay's UK website lists gift cards, the Worldpay Dashboard, Insights reporting, DCC and multicurrency pricing, pay-by-link, invoicing, a Virtual Terminal, dispute management, FraudSight, a business cash advance and SaferPayments. Availability and pricing depend on the business, so confirm the details with Worldpay.
Are there loyalty programmes for Worldpay merchants?
Yes. Worldpay offers gift, reward and stored value solutions, and Zeal adds card-linked loyalty on supported Worldpay payment terminals, with no app or plastic card. Our guide to value-added services on payment terminals explains how payment providers offer such services.
Does Zeal change how I take payments with Worldpay?
No. Zeal runs next to the payment app, does not process payments and does not change how you take payments or when you are paid. Worldpay continues to process every payment.
Which Worldpay payment terminals work with Zeal?
Supported models vary, so we confirm your exact terminal before anything is switched on. Register on getzeal.io and we will check your Worldpay setup with you.
Is a Worldpay business cash advance a loan?
Worldpay says its business cash advance, provided with Liberis, is not a loan. It is repaid as a fixed percentage of card sales, with one fixed fee and no APR.
Sources
- Worldpay, Small business, Gift card solutions, Loyalty and gift, Worldpay Dashboard and Reporting and insights, checked 10 October 2026.
- Worldpay, Multicurrency solutions, In-store payments, Virtual terminal, Dispute management and Fraud prevention, checked 10 October 2026.
- Worldpay, Business cash advance, SaferPayments and Card payment machines, checked 10 October 2026.
- UK Finance, UK Payment Markets 2026 (summary), August 2026.
- Payment Systems Regulator, PS22/2 Card-acquiring market remedies: final decision, 6 October 2022.
- PCI Security Standards Council, PCI DSS, Just published: PCI DSS v4.0.1 (11 June 2024), FAQ 1301 and tokenisation guidelines (information supplement).
- Information Commissioner's Office, Pseudonymisation and Legitimate interests (updated 23 March 2026).
About the author
Omar Ebeid is Co-founder and CEO of Zeal, which he founded with Bellal Mohamed in 2019. He holds an MSc in Entrepreneurship from the University of Bath and won the Vice-Chancellor's Award at the University of Surrey. Under his leadership Zeal won Team of the Year at the UK FinTech Awards 2026 and Platinum at the Juniper Research Future Digital Awards 2023, and has raised $14 million in total, including a $10 million pre-Series A round announced on 9 September 2026. Connect with Omar on LinkedIn.
You might also like